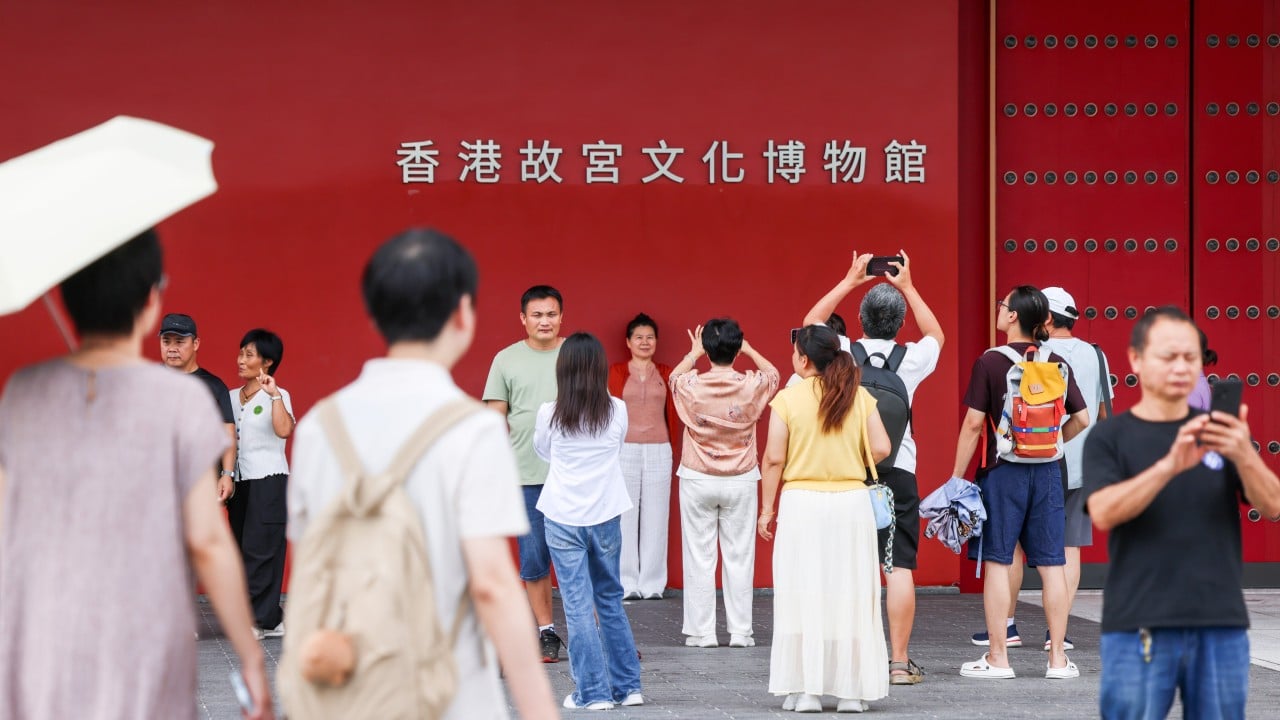
Hong Kong's crown jewel of culture is bleeding money, and the band-aids won't hold much longer.
The West Kowloon Cultural District Authority just reported a widening deficit of HK$998 million for the 2025/26 financial year. That is a sharp jump of nearly 30 percent from the previous year, driven largely by preparation costs for the upcoming WestK Performing Arts Centre and rising operational expenses. To stay afloat, the authority is pinning its immediate hopes on upcoming residential property tenders and a combination of loans and bonds.
Property development is a handy cash injection, but experts are warning that land sales offer only temporary relief for the West Kowloon arts hub. If you rely on real estate cycles to fund high-culture institutions, you are building your foundation on quicksand.
The Core Problem with Real Estate Funding
The original financial model handed to the West Kowloon Cultural District Authority relied on an endowment model tied to property development rights. The idea was simple. Build commercial and residential towers, sell or lease them out, and use the continuous revenue stream to subsidize museums, theaters, and public art spaces.
It sounds smart on paper. In practice, the property market does not care about cultural mandates.
When property values slump or market sentiment shifts, the expected cash cow goes dry. Relying on land sales means the arts hub's survival becomes chained to Hong Kong's notoriously volatile real estate sector. You cannot run a world-class center for the performing arts and world-class museums like M+ and the Palace Museum if your budget swings wildly based on whether a single residential site hits its reserve price.
Short-Term Fixes Versus Structural Reform
The authority has tried to patch the bleeding through debt financing. Earlier this year, the operator secured a HK$3 billion, 10-year loan facility alongside a US$1 billion bond issuance program. Revenues have actually grown, hitting HK$768 million with the cost recovery rate inching up from 37 percent to 40 percent.
More visitors are walking through the gates. More tickets are being sold. But income growth is completely swallowed by the sheer expense of running large-scale cultural facilities.
Loans buy time. Land sales buy breathing room. Neither of them creates a permanent structural solution.
When those residential plots are sold, the cash arrives once. Once the money is spent, it's gone. You cannot sell the same piece of land twice. Experts point out that using one-off capital gains from real estate to cover recurrent operating expenditures is a classic financial trap.
What a Sustainable Model Actually Looks Like
If West Kowloon wants to survive without running back to the government for repeated rescues or leaning exclusively on property developers, things have to change.
First, the cost recovery rate has to climb higher. While hitting 40 percent is an improvement, major cultural districts globally rely on a mix of robust endowment funds, aggressive philanthropic giving, corporate sponsorships, and diversified commercial operations that do not depend solely on property sales.
Second, the operating model needs a hard look. Expanding footprints and opening new venues like the performing arts centre drives up utility costs, staffing needs, and maintenance bills instantly. Scaling up operations before achieving financial stability creates a compounding deficit.
Land sales can buy a few years of operational runway, but they are a distraction from the real work. Stop treating real estate as an eternal endowment. Fix the underlying revenue model or watch the cultural hub struggle from one financial crisis to the next.